Περιεχόμενα Άρθρου
Shell Companies in the EU –Fighting Tax Evasion
The new Directive of the European Commission aims to combat the abuse of shell companies*, which will limit unfair competition and ensure fair taxation.
*companies without physical presence and real economic activity
According to this initiative, companies based in the EU and showing zero or minimal economic activity will not benefit from the tax advantages of certain states (such as Ireland, Bulgaria, Cyprus, etc.) with favorable tax regimes. EU member states must comply with the Directive by March 30, 2023, in order to implement it from January 1, 2024.
How does it contribute to the fight against tax evasion?
By introducing objective indicators (such as income, human resources, and the place of establishment of the companies) the Directive foresees the strengthening of the identification of virtual companies. Using these indicators, but also in cooperation with each other, the tax authorities of the member states will be able to accurately identify virtual companies and impose the corresponding sanctions on them.
Article to read:
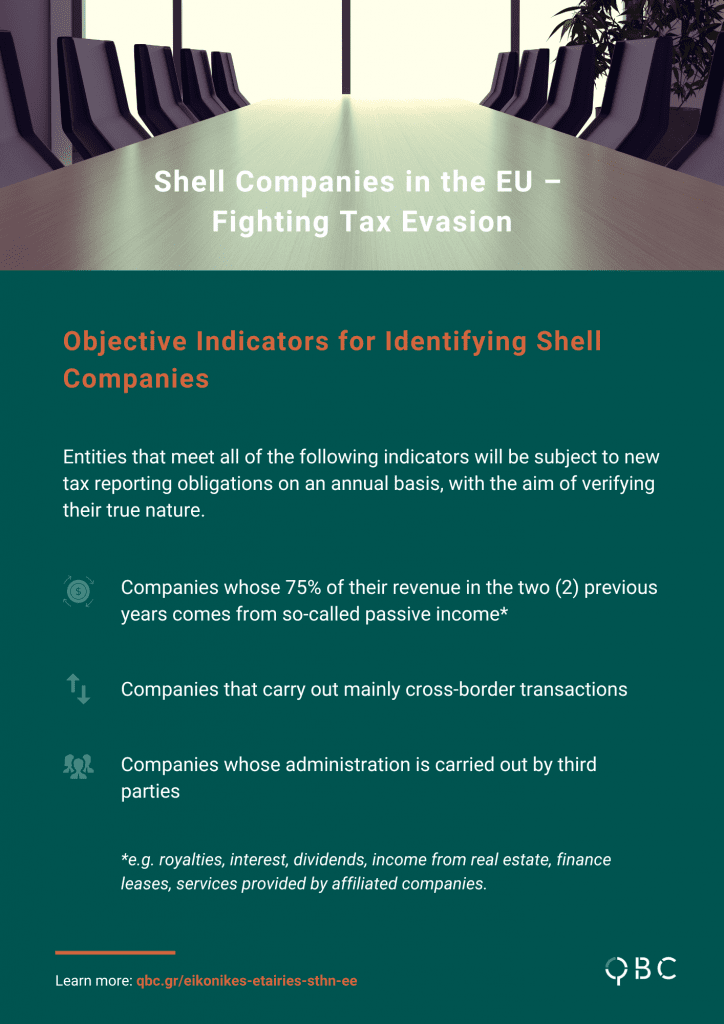
Objective Indicators for Identifying Shell Companies
Entities that meet all of the following indicators will be subject to new tax reporting obligations on an annual basis, with the aim of verifying their true nature.
- Companies whose 75% of their revenue in the two (2) previous years comes from so-called passive income*
- Companies that carry out mainly cross-border transactions
- Companies whose administration is carried out by third parties
*e.g. royalties, interest, dividends, income from real estate, finance leases, and services provided by affiliated companies.
Obligations of Companies that meet the Objective Indicators
Entities that meet the above indicators must indicate in their annual tax return that they have met the minimum status indicators.
The minimum status indicators concern:
- The exclusive ownership of their own facilities
- The existence of their own active bank account within the EU
- The employment of at least one director who is a tax resident in the same country as the company exists and also deals exclusively with the company’s activities or the majority of the company’s employees are tax residents of the same country
The fulfillment of the above minimum status indicators must be sufficiently proven by relevant documents, accompanying the tax return.
In the event that a company meets the above objective indicators and is deemed to have no substance, it may still be exempted from the application of the Directive. In order to be exempted, it must prove to the relevant tax authorities that its establishment concerns commercial activity and does not aim at tax evasion.
Management of Shell Companies by Tax Authorities
As long as the tax authorities of the respective member state have all the information required to characterize the company as a shell, then the company loses the right to receive a certificate of tax residence. This means, among other things, that now the company: Is not entitled to the protection of bilateral double taxation treaties It is not entitled to the application of the Parent-Subsidiary Directive for exemption from withholding tax on dividends It is not entitled to the application of the Royalty and Interest Directive
For the recognition of shell companies, the tax authorities of the member states will exchange relevant information with the other member states. Each member state will determine the sanctions it will impose on virtual companies established within it. The European Commission Directive recommends the imposition of a fine of at least equal to 5% of the virtual company’s turnover.
Companies have the right to present arguments and evidence of course to the contrary. If the objection is not accepted by the tax authorities, the fine applies for the relevant year and for another 5 years, as long as the actual circumstances do not change.
Article to read:
QBC – Quality Business Consultants
QBC satisfies a wide range of needs related to companies’ financial and accounting requirements, regardless of their size and industry. In particular, we offer customized accounting outsourcing solutions tailored to the particular needs of our clients.
Our team consists of highly qualified Accountants, Tax Professionals, Business Consultants, and Internal Auditors. This strategic composition of our team provides a competitive advantage, that of supporting businesses in multiple ways.
Keeping abreast of the latest developments in tax legislation, QBC is at your side to help you achieve maximum tax compliance and benefit for your business.
For more information about corporate taxation, you can contact us by phone at 216 900 7576 or submit a contact request.