Περιεχόμενα Άρθρου
Debt-Equity Bias
In the majority of European Union member states, debt financing is surrounded by a more favorable tax framework than equity financing. The favorable tax treatment lies in the fact that the payment of interest on loans is deductible when calculating corporate income tax, whereas, in contrast, costs related to equity financing, such as dividends, are usually not deductible.
As a result, this asymmetric tax treatment of the two forms of financing increases the chances that a company will be positively positioned in one form of financing, through debt rather than equity capital, based on unequal tax treatment even if its business model suggested otherwise.
Over-indebtedness could threaten the stability of the financial system and increase the risk of bankruptcies, which in turn would increase unemployment.
DEBRA Directive
The European Commission through the new DEBRA Directive aims to address the asymmetric tax treatment between debt and equity financing by removing taxation as a factor when choosing a form of financing.
Through the DEBRA Directive, the European Commission proposes that the costs incurred during equity financing be deducted from the company’s income tax, just as in the case of debt financing.
Under the initiative, a premium will be introduced for new equity-financed investments to mitigate the favorable treatment of debt. The regime will include a set of strict anti-avoidance rules to ensure tax fairness.
In addition, it proposes a more favorable tax credit for small and medium-sized enterprises (SMEs), given the difficulty they face in finding equity capital compared to larger enterprises.
Διαβάστε επίσης:
Why is it important to address asymmetric tax treatment?
Addressing asymmetric tax treatment could help revalue companies, making them stronger and more resilient to shocks.
Equity is also particularly important for fast-growing innovative companies (startups & scale-ups) in their early stages and for companies wishing to expand globally.
The green and digital transition require new investments in innovative technologies. More than 50% of green investments in the coming years are estimated to come from new technologies, which require more risk financing. Equality will therefore play an important role in promoting the sustainable transition to a greener economy and Europe’s overall growth and economic stability.
How will the DEBRA Directive address asymmetric tax treatment?
The equity provision will be calculated based on the difference between the net equity at the end of the current tax year and the net equity at the end of the previous tax year, multiplied by a notional interest rate. This means that the allowance will only be granted for the sum of equity increases in a particular year.
The notional rate is the 10-year risk-free rate for the relevant currency, plus a 1% risk premium or, in the case of SMEs, a 1.5% risk premium. The home equity allowance is deductible for 10 consecutive tax years if it does not exceed 30% of the taxpayer’s taxable income. In addition, if the equity provision is higher than the taxpayer’s net taxable income, the taxpayer can carry forward the excess equity provision without time limit.
Taxpayers will also be able to carry forward unused equity allowance more than 30% of taxable income, for a maximum of 5 tax years.
Finally, the proposal introduces a 15% reduction in the debt interest deduction, to better mitigate the debt-equity bias, not only on the equity side but also on the debt side.
DEBRA Directive and BEFIT Proposal
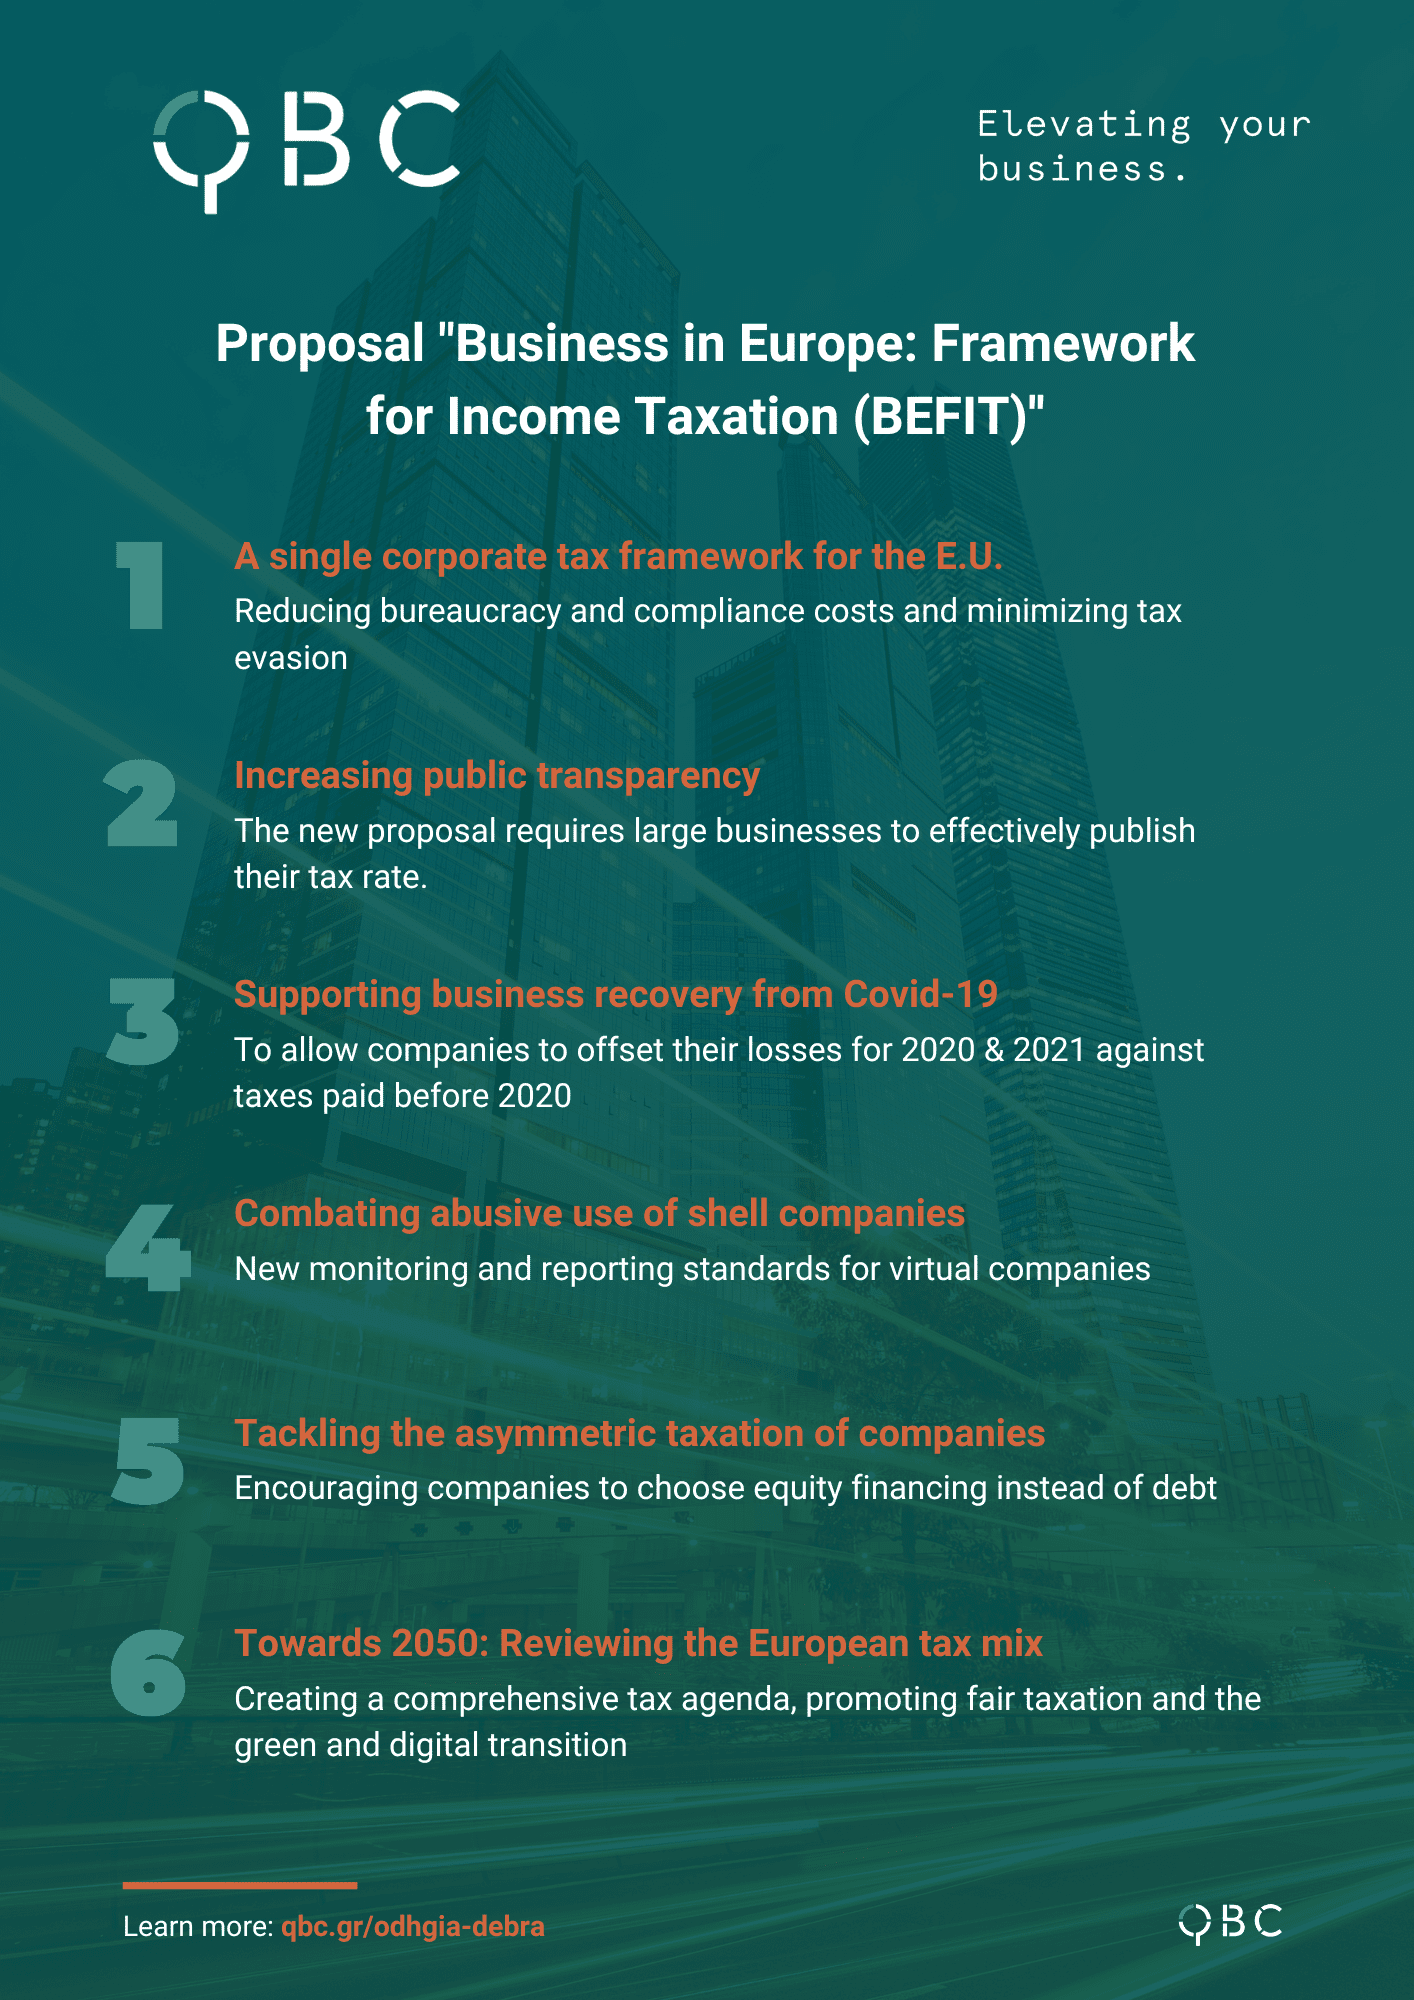
The DEBRA Directive (Debt-Equity Bias Reduction Allowance) in the context of the Proposal “Business in Europe: Framework for Income Taxation (BEFIT)” aims to create a single corporate taxation manual for the EU. and is part of the European Commission’s long-term vision to create a fairer and more sustainable business environment and includes targeted measures to promote productive investment and entrepreneurship to ensure effective taxation.
The objectives of the “BEFIT” Proposal concern the creation of a harmonized tax framework for EU companies, the strengthening of public transparency of large companies, the support of companies affected by the Covid-19 pandemic and especially SMEs, the tackling the abusive use of virtual companies, tackling the asymmetric tax treatment between debt financing and equity financing (Debt-Equity Bias).
Timetable of the “DEBRA” Directive
The European Commission proposes 1.1.2024 as the date for the integration of the Directive by the EU member states. The successful integration of the Directive depends on the unanimous decision of the member states.
Διαβάστε επίσης:
QBC – Quality Business Consultants
QBC satisfies a wide range of needs related to companies’ financial and accounting requirements, regardless of their size and industry. In particular, we offer customized accounting outsourcing solutions tailored to the particular needs of our clients.
Our team consists of highly qualified Accountants, Tax Professionals, Business Consultants, and Internal Auditors. This strategic composition of our team provides a competitive advantage, that of supporting businesses in multiple ways.
Keeping abreast of the latest developments in tax legislation, QBC is at your side to help you achieve maximum tax compliance and benefit for your business.
For more information about corporate taxation and specifically the “DEBRA Directive”, you can contact us by phone at 216 900 7576 or submit a contact request.