
Περιεχόμενα Άρθρου
Holding Companies in Greece: Favorable institutional framework
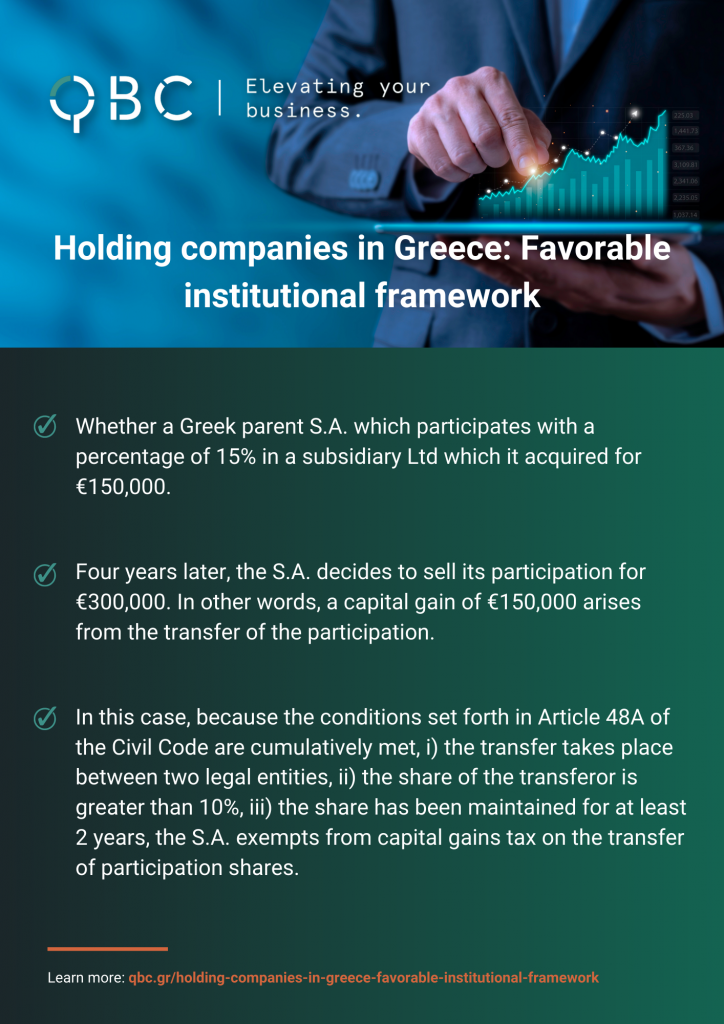
Article 48A of the Income Tax Code stipulates that Greek companies can now be exempted from income tax for the capital gain arising from the transfer of shares.
With the validity of these provisions, Greece increases its competitiveness, establishing its own favorable institutional framework for the creation of holding companies.
In this way, Greece seeks to become an attractive option for establishing Greek holding companies, as it allows them. Also, establishing this framework can be another incentive to attract foreign capital.
Article to read:
What is defined as a holding company
Holding companies usually do not make or sell products or services. Usually, the primary purpose of a holding company is the collection of dividends from the investment in other companies and ideally the future sale of the shares (transfer of shares).
What is defined as goodwill
Specifically, goodwill is recognized as the difference between the purchase and sale prices. Expenses incurred by the taxpayer and directly related to the purchase or sale of the securities are included in the acquisition price and the sale price and, by extension, form the final capital gain.
What is defined as a transfer of shares
In particular, any act of transfer of securities is recognized as a transfer of shares, such as, for example, the sale of securities, the contribution of shares to cover or increase the capital of a company, the exchange of securities, the transfer of sharesin the context of a capital reduction, as well as the distribution of dividends.
Article to read:
Conditions for application of capital gains tax exemption
For the exemption from capital gains tax to be effective upon the transfer of the securities, cumulative conditions must be met in the case of the person transferring the securities (conditions of the 1st legal entity), as well as of the person to whom the securities are transferred (conditions of the 2nd legal entity).
Conditions of 1st legal entity
- To be a legal entity that specifically has one of the following forms: Private Company (PC), Limited Company (Ltd), Société Anonyme (SA), Personal Unlimited Partnership (OE) and Personal Limited Partnership (EE)
- To be a tax resident of Greece,
- The legal entity transferring the securities to me participates at least with a percentage of 10%,
- The legal entity has maintained said participation for at least 2 years (24 months).
Conditions of 2nd legal entity
- To be a legal entity which specifically is a Private Company (PC), Limited Company (Ltd), Société Anonyme (SA), Personal Unlimited Partnership (OE) and Personal Limited Partnership (EE)
- To be a tax resident of an EU member state,
- To be subject to taxation in the state where he declares himself a resident.
How can QBC help you?
Keeping abreast of the latest developments in tax legislation, QBC is at your side to help you achieve maximum tax compliance and benefit for your business.
Through transfer pricing services, QBC undertakes to support you in the establishment, submission, and renewal of the documentation file, as well as during the tax audit by the Tax Authorities.
For more information on corporate tax and accounting, you can contact us by phone at 216 900 7576 or submit a contact request and one of our Consultants will serve you immediately.