Περιεχόμενα Άρθρου
Transfer Pricing Fines – Tax Audits
In their effort to reduce the tax revenue deficit that has widened in recent years, the Tax Authorities are intensifying tax audits, as well as the fines and penalties they impose.
The focus of the European Commission’s attention is the Tax Action Plan with the goal of consolidating a fairer, simpler, and more efficient tax system. One of the main tools that the E.U. to achieve this purpose are tax audits and the imposition of fines and penalties if tax violations are detected.
Specifically, in the case of transfer pricing tax audits, the Independent Public Revenue Authority has integrated them into its general strategy on tax audits and intends to follow a stricter approach.
The best weapon companies have to effectively manage tax audits is proactive tax compliance with the relevant provisions.
Below, we analyze five (5) cases regarding the documentation of transfer pricing, a high-risk area for companies that do not seek tax compliance and are asked to shoulder the relevant fines.
Article to read:
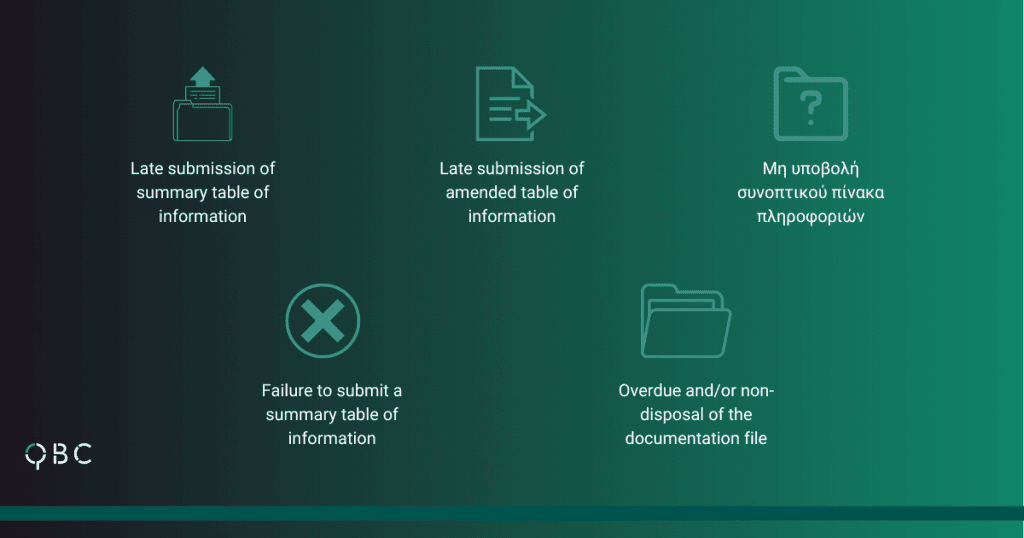
The imposition of fines is distinguished based on five (5) cases:
- Late submission of summary information table
- Late submission of amended information table
- Failure to submit a summary information table
- Submitting an inaccurate or incomplete summary information table
- Overdue and/or non-delivery of the documentation file to the Tax Administration
First of all, let’s note that companies that carry out intra-group transactions have four (4) months from the end of the tax year to submit the Summary Information Table (SIP) electronically.
Case 1 – Late submission of summary information table
If a company does not submit the SIP within four (4) months, then a fine of 1/1000 (0.1%) of the transactions to be documented is imposed on it.
Also, the fine that will be imposed on the company cannot be less than five hundred (500) euro and more than two thousand (2,000) euro.
Article to read:
Case 2 – Late submission of the amended table of information
Furthermore, for the companies that have submitted the SIP by the deadline but submitted after the end of four (4) months an amending table of information, the above fine is also imposed. Provided that the amendment changes the transactions to be documented for an amount greater than two hundred thousand (200,000) euro.
Case 3 – Failure to submit a summary table of information
Now, if the company does not submit the SPP at all, the fine imposed on it corresponds to 1/1000 of the transactions to be documented. Of course, the fine cannot be less than two thousand five hundred (2,500) euro and greater than ten thousand (10,000) euro.
Case 4 – Submission of inaccurate or incomplete summary information table
Regarding the submission of an inaccurate or incomplete SIP, the penalty imposed on the company, as well as the permissible limits, are the same as in the case of late submission. By the terms inaccurate or incomplete SIP, we mean that there is an inaccuracy of at least 10% in terms of the transactions that need documentation.
Case 5 – Overdue and/or non-disposal of the documentation file
Finally, the company has thirty (30) days from the day of notification of the relevant invitation to submit the Documentation File to the Tax Administration. If she exceeds this time limit, a fine is imposed on her. The value of the fine is determined based on the time delay in submitting the Documentation File.
If the file is submitted to the Tax Administration from the thirty-first (31st) day up to the sixtieth (60th) day, then the company incurs a fine of five thousand (5,000) euro.
If the file is submitted to the Tax Administration from the sixty-first (61st) day to the ninetieth (90th) then a fine of ten thousand (10,000) euro is imposed on the company.
If the file is not submitted at all or is submitted after the ninetieth (90th) day to the Tax Administration, then the fine amounts to twenty thousand (20,000) euro.
To avoid the above fines, companies must take a proactive stance in order to be able to effectively manage the upcoming transfer pricing tax audit.
How can QBC help you?
Keeping abreast of the latest developments in tax legislation, QBC is at your side to help you achieve maximum tax compliance and benefit for your business.
Through transfer pricing services, QBC undertakes to support you in the establishment, submission, and renewal of the documentation file, as well as during the tax audit by the Tax Authorities.
For more information on corporate tax and accounting, you can contact us by phone at 216 900 7576 or submit a contact request and one of our Consultants will serve you immediately.